Running payroll in Switzerland looks straightforward until you factor in cantonal tax tables, withholding tax rules and three layers of social contributions. For a small or medium-sized company, the real question is rarely “can we do it?” but “should we?”. The answer depends on the regulatory complexity you are willing to carry internally, the number of employees concerned and the share of staff subject to withholding tax.
Direct answer: Outsourcing payroll makes sense when the combination of cantons, employee profiles and withholding tax cases creates a workload or risk level your HR or finance team cannot absorb reliably. Below a certain volume and complexity, a well-equipped internal process can remain competitive.
What payroll outsourcing means for Swiss companies
Payroll outsourcing means transferring the operational production of your payslips to an external provider. The provider calculates gross-to-net amounts, applies social contributions, produces payslips, prepares year-end salary certificates and files the required declarations to AHV/IV/EO offices, pension funds (LPP/BVG), accident insurers and cantonal tax authorities. Your company remains the legal employer and retains full responsibility toward employees and administrations.
In-house payroll, by contrast, keeps all of these tasks within your HR or finance team, usually with a dedicated software or sometimes a shared spreadsheet for very small structures. The split is not binary: many SMEs use a hybrid model, where HR enters variable data (hours, bonuses, absences) and the provider runs the calculation and filings.
The typical scope of an outsourced service covers monthly gross-to-net calculation, deductions for social insurances, withholding tax for concerned employees, electronic transmission of declarations (ELM standard), issuance of payslips, year-end certificates and ad hoc reports for accounting. It generally does not cover HR decisions, contracts or disputes with employees, which stay with the employer.
A common scenario: a Swiss SME with twelve employees managed payroll on a spreadsheet maintained by its accountant. After hiring two cross-border workers subject to withholding tax in a different canton, the complexity jumped and the company moved to an outsourced provider to avoid monthly recalculation errors. Before signing, running a simulation to calculate payroll costs in Switzerland can help put the discussion with a provider on concrete ground.
Why Swiss payroll compliance is harder than it looks?
Swiss payroll compliance is demanding because three regulatory layers overlap: federal social insurances, occupational pension rules and cantonal tax administration. Each layer has its own rates, thresholds and reporting formats, and each error can trigger retroactive corrections.
According to the SECO contribution overview, AHV/IV/EO contributions represent 10.6 % of gross salary (AHV 8.7%, IV 1.4%, EO 0.5%), to which unemployment insurance (ALV) adds 2.2%. These amounts are split equally between employer and employee. On top of this, LPP/BVG (occupational pension) contributions, accident insurance (UVG/LAA) and family allowance contributions apply, with rates that vary by pension plan, canton and risk class.
Withholding tax and cantonal variability
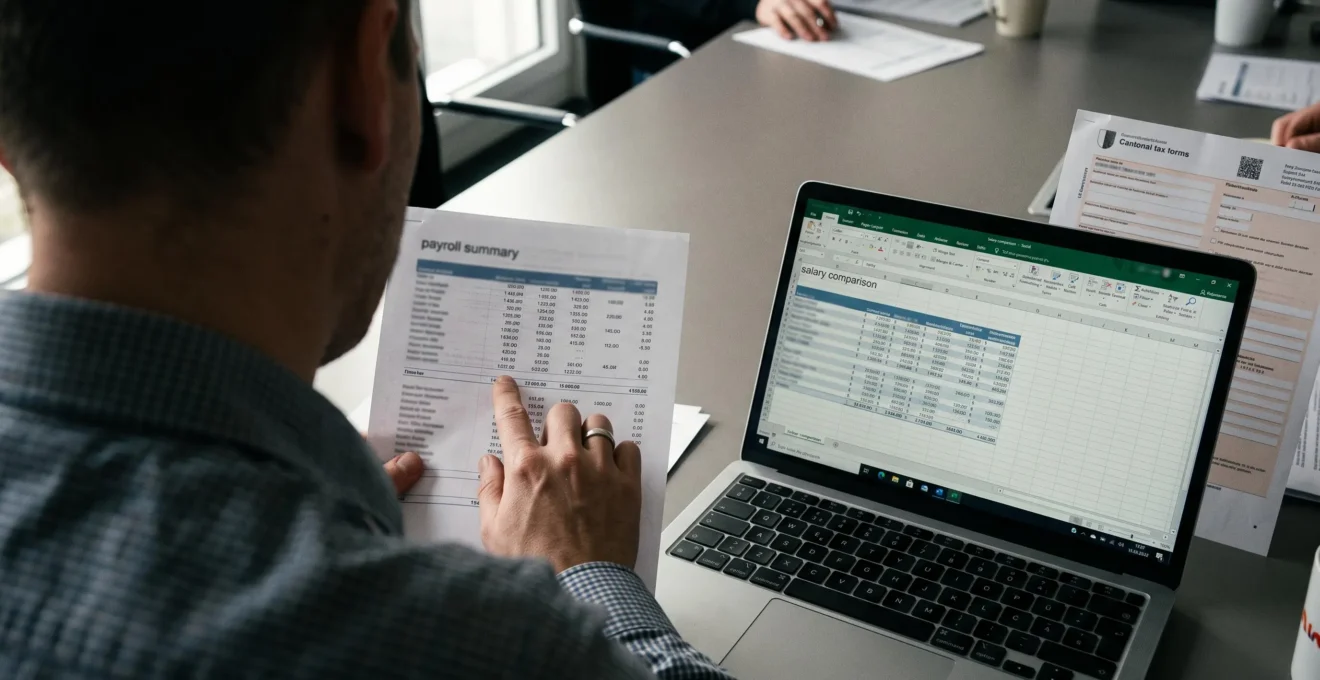
Withholding tax (Quellensteuer) applies to specific categories of employees, typically foreign workers without a C permit and certain cross-border workers. The complexity comes from the tariff structure: as confirmed by the Federal Tax Administration page on cantonal withholding tax, “Der Tarif für die Quellensteuer ist kantonsabhängig” — the applicable tariff depends on the canton and must be checked with the competent cantonal tax authority.
In practice, an employee living in Fribourg but working in Vaud, or a cross-border worker from France employed in Geneva, will trigger different tariffs, codes and declaration channels. A payroll officer must identify the correct canton of taxation, the right tariff code (depending on family situation and additional income) and apply the version of the tariff in force for the reporting period.
Consequences of errors
Errors on withholding tax, missed thresholds for LPP affiliation or wrong contribution bases usually surface during year-end reconciliation or audits. They lead to retroactive corrections across several months, interest charges, administrative follow-ups and, in some cases, formal penalties. Beyond the financial impact, the HR workload required to rebuild correct files is often underestimated.
Legal responsibility remains with the employer: Outsourcing payroll transfers the operational workload, not the legal liability. Declarations, payments and corrections toward Swiss social insurances and tax authorities remain the employer’s responsibility, including when a provider makes an error.
This regulatory density is widely perceived as a burden. A 2024 survey published by the Centre Patronal survey on labour law concerns found that legal complexity was the top concern for 40 % of surveyed Swiss companies regarding labour law and social insurance obligations, well ahead of labour shortage (27%) and absenteeism (18%).
In-house payroll or outsourced payroll: which option fits your company?
The choice between in-house and outsourced payroll rarely depends on a single factor. It combines headcount, cantonal footprint, share of employees subject to withholding tax, available internal expertise and tolerance for risk. The table below summarises how the two models compare on the dimensions that matter most for an SME.
| Criterion | In-house payroll | Outsourced payroll |
|---|---|---|
| Legal responsibility | Employer | Employer (unchanged) |
| Operational workload | Internal HR / finance team | Transferred to provider |
| Required expertise | Updated in-house for AHV, LPP, Quellensteuer | Held by the provider |
| Cost structure | Salary time + software + training | Fee per payslip or monthly package |
| Control over data | Full internal control | Shared with provider (contract-based) |
| Risk of errors | Depends on internal expertise | Depends on provider quality |
Costs: what you actually compare
Comparing costs honestly means putting the full internal cost opposite the provider fee. Internal cost includes the share of HR or accounting time spent on payroll, the payroll software licence, training to keep up with regulatory updates and the time dedicated to year-end operations. Outsourced cost is usually structured as a setup fee plus a recurring fee per payslip or per employee per month.
For very small structures (fewer than five employees, single canton, no withholding tax), in-house processing with a modern tool often remains the most economical option. For SMEs with 10 to 50 employees, several cantons involved or recurring withholding tax cases, the balance frequently tips toward outsourcing because the regulatory maintenance cost no longer scales with volume.
Decision factors beyond cost
- Fewer than 5 employees, one canton, no withholding tax:In-house with dedicated software is usually sufficient.
- 5 to 20 employees, one or two cantons, few withholding tax cases:Hybrid model or outsourcing depending on internal expertise.
- More than 20 employees or several cantons or regular withholding tax cases:Outsourcing generally reduces risk and total cost of ownership.
- No qualified payroll officer in-house:Outsourcing avoids over-reliance on a single person.
Control over data is a legitimate concern, but it is addressed contractually. A serious provider documents data location, access rights, confidentiality clauses and procedures in case of incident. The actual question is less “do we lose control?” than “do we define control precisely in the contract?”.
How to choose the right payroll provider in Switzerland
Choosing a provider should be treated as a procurement project, not as a simple quote comparison. The goal is to verify that the provider masters Swiss specifics and that the service level matches your operational constraints.
Key criteria to evaluate systematically:
- Swiss regulatory expertise: command of AHV/IV/EO, ALV, LPP/BVG, UVG, family allowances and cantonal withholding tax tariffs, including recent changes.
- Cantonal coverage: ability to handle all cantons where your employees live and work, not only the canton of your head office.
- Data security: hosting location, access management, encryption, backup, incident procedures and compliance with the Swiss Federal Act on Data Protection (nFADP).
- Service level: deadlines for monthly cycles, named contact person, response time for queries, handling of corrections and liability clauses.
- Pricing transparency: clear breakdown between setup, monthly fees, extras (year-end, corrections, new hires) and termination conditions.
- Reporting and tool integration: compatibility with your accounting software, export formats and employee self-service options.
During a first contact, useful questions include: how many Swiss clients do you serve and in which cantons? Who is my dedicated contact and what is their qualification? What happens if a declaration error is attributable to your service? How do you handle a mid-month employee entry or departure? What is your process for annual tariff updates? Clear, documented answers signal a provider used to Swiss payroll realities.
Two points deserve particular attention. First, continuity of year-to-date accumulators: AHV, ALV and LPP contributions have annual caps and reference bases that must be transferred exactly, otherwise end-of-year reconciliations will show gaps. Second, retention of historical data: Swiss rules require payroll records to be kept for several years, and the ownership and location of this archive should be clarified before the switch, not after.
Simulate before deciding: Before signing with any provider, build a side-by-side comparison of your current internal cost (time, software, training) and the full outsourcing fee, including year-end and ad hoc operations. A written simulation prevents surprises in the second year of contract.
Choosing a payroll solution is also a decision about how you want to allocate attention inside the company. Clean, reliable payroll is one of the financial foundation of your business, and the model that supports it should match your real complexity, not an idealised version of it.
Does outsourcing payroll transfer legal responsibility to the provider?
No. The employer remains legally responsible toward employees, social insurances and tax authorities. The provider executes operations under a service contract, which can define financial liability in case of proven error, but statutory obligations stay with the employer.
From what headcount does outsourcing payroll become relevant?
There is no universal threshold. The decisive factors are the number of cantons involved, the share of employees subject to withholding tax and the presence of qualified payroll expertise in-house. Many SMEs consider outsourcing between 10 and 20 employees, earlier if cantonal or withholding tax complexity is high.
How is data protection ensured when payroll is outsourced?
Through contractual clauses aligned with the revised Swiss Federal Act on Data Protection (nFADP): defined data location, access management, confidentiality obligations, incident notification and conditions for data return at contract end. These points should be verified before signing, not assumed.
Can the switch to an external provider happen mid-year?
Yes, provided year-to-date accumulators for AHV, ALV, LPP and withholding tax are transferred exactly. A parallel cycle before go-live is strongly recommended to avoid discrepancies during year-end reconciliation.
This article provides general information on payroll organisation in Switzerland and does not constitute individual legal, tax or social insurance advice. Rates, thresholds and cantonal rules evolve; verify the current provisions with the competent authorities or a qualified professional before making a decision.